
The Line Down the Middle of Kansas City
Kansas and Missouri income tax rates compared, the Kansas City earnings tax, and the residency questions worth asking before a move across the state line.
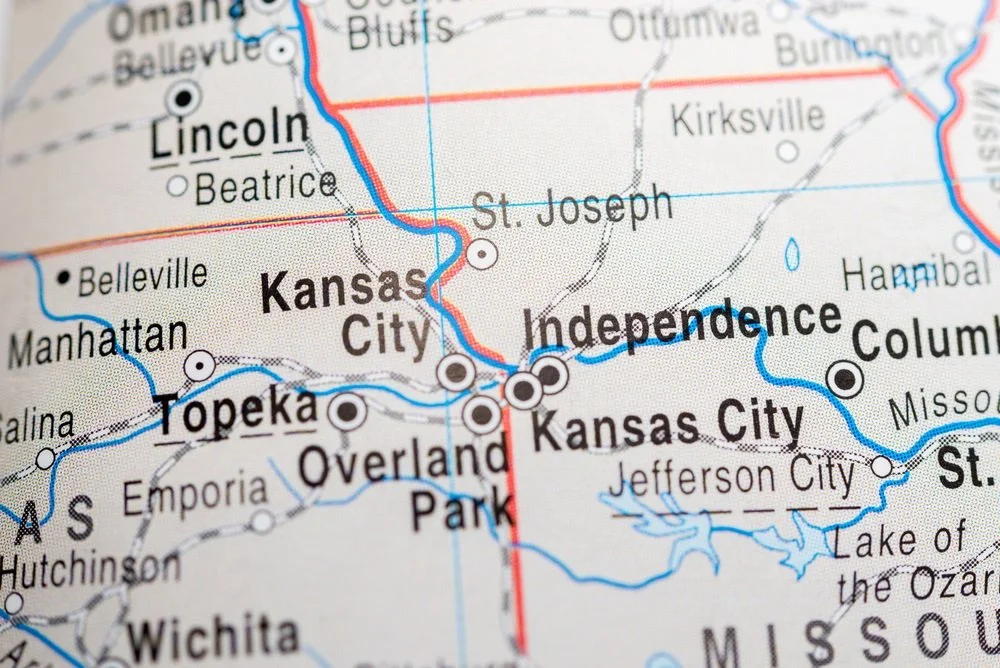
Kansas and Missouri meet in the middle of where our clients live and work. Depending on which side of that line your address sits on — and which side your office sits on — the difference is real, recurring, and calculable. National content never addresses it.
The Rate Difference
For 2026, Kansas has two brackets: 5.20% on taxable income up to $23,000 ($46,000 for joint filers) and 5.58% above that. Because the second bracket starts so low, most higher earners pay 5.58% on nearly all of their income. Missouri has more brackets on paper, but its top rate of 4.7% starts at roughly $9,000 of taxable income, so it works the same way. In practice, the comparison comes down to one number against the other: 5.58% versus 4.7%
The Difference That Dwarfs the Rate
Missouri no longer taxes capital gains. For tax years beginning in 2025, individual filers subtract 100% of capital gains reported federally — short-term and long-term alike. Kansas taxes them as ordinary income at up to 5.58%.
For a household selling a business, unwinding a concentrated position, or closing on appreciated real estate, that gap is worth far more than the 0.88 percentage points separating the two income tax rates. On a $2 million gain, it is roughly $111,600 of Kansas tax that Missouri does not charge. This is one place where the state line can move a major decision.
Estate tax, by contrast, is a non-issue on both sides. Neither Kansas nor Missouri imposes an estate tax or an inheritance tax. Only the federal rules apply, and they apply identically in Overland Park and Brookside.
The Kansas City Earnings Tax
If you work inside Kansas City, Missouri's city limits, a 1% earnings tax applies to wages earned there — for residents and non-residents alike. Live in Overland Park and commute to a downtown office and you owe the earnings tax on income earned at that location, even as a Kansas resident.
Kansas residents can claim it back. Since 2015, Kansas has allowed the earnings tax to be included in the credit for income taxes paid to another state — so the Overland Park commuter above is not paying it twice. Missouri residents get no equivalent credit, because Missouri does not credit a local tax imposed inside its own borders.
Retirement Income Is Less Different Than You'd Think
Both states now fully exempt Social Security retirement benefits. Kansas removed its income cap in 2024; Missouri removed its thresholds the same year. That is the single largest line item for most retired households.
Pensions are where they diverge, though less than you'd expect. Kansas exempts federal civil service, military, railroad, and Kansas public pensions outright, with no income limit. Missouri exempts public pension income up to the maximum Social Security benefit amount, but the exemption is reduced by any Social Security benefit deduction claimed.
Private pensions are the exception — Missouri's $6,000 deduction phases out at $25,000 of income for a single filer ($32,000 for joint filers), so most of our clients private pension income is fully taxable in both states.
Why This Belongs in a Plan, Not a Moving Decision
We rarely see families relocate for a rate difference alone, and that is sound judgment — proximity to grandchildren outranks a tax bracket every time. But for anyone already weighing a move for other reasons, or deciding where to establish primary residency during a year of unusually high income, the math is worth running before the decision rather than after.
Want to learn more about private wealth planning?
This content is provided by Windward Private Wealth Management Inc. (“Windward” or the “Firm”) for informational purposes only. Investing involves the risk of loss and investors should be prepared to bear potential losses. No portion of this blog is to be construed as a solicitation to buy or sell a security or the provision of personalized investment, tax or legal advice. Certain information contained in the individual blog posts will be derived from sources that Windward believes to be reliable; however, the Firm does not guarantee the accuracy or timeliness of such information and assumes no liability for any resulting damages.
Windward is an SEC registered investment adviser. The Firm may only provide services in those states in which it is notice filed or qualifies for a corresponding exemption from such requirements. For information about Windward’s registration status and business operations, please consult the Firm’s Form ADV disclosure documents, the most recent versions of which are available on the SEC’s Investment Adviser Public Disclosure website at www.adviserinfo.sec.gov.